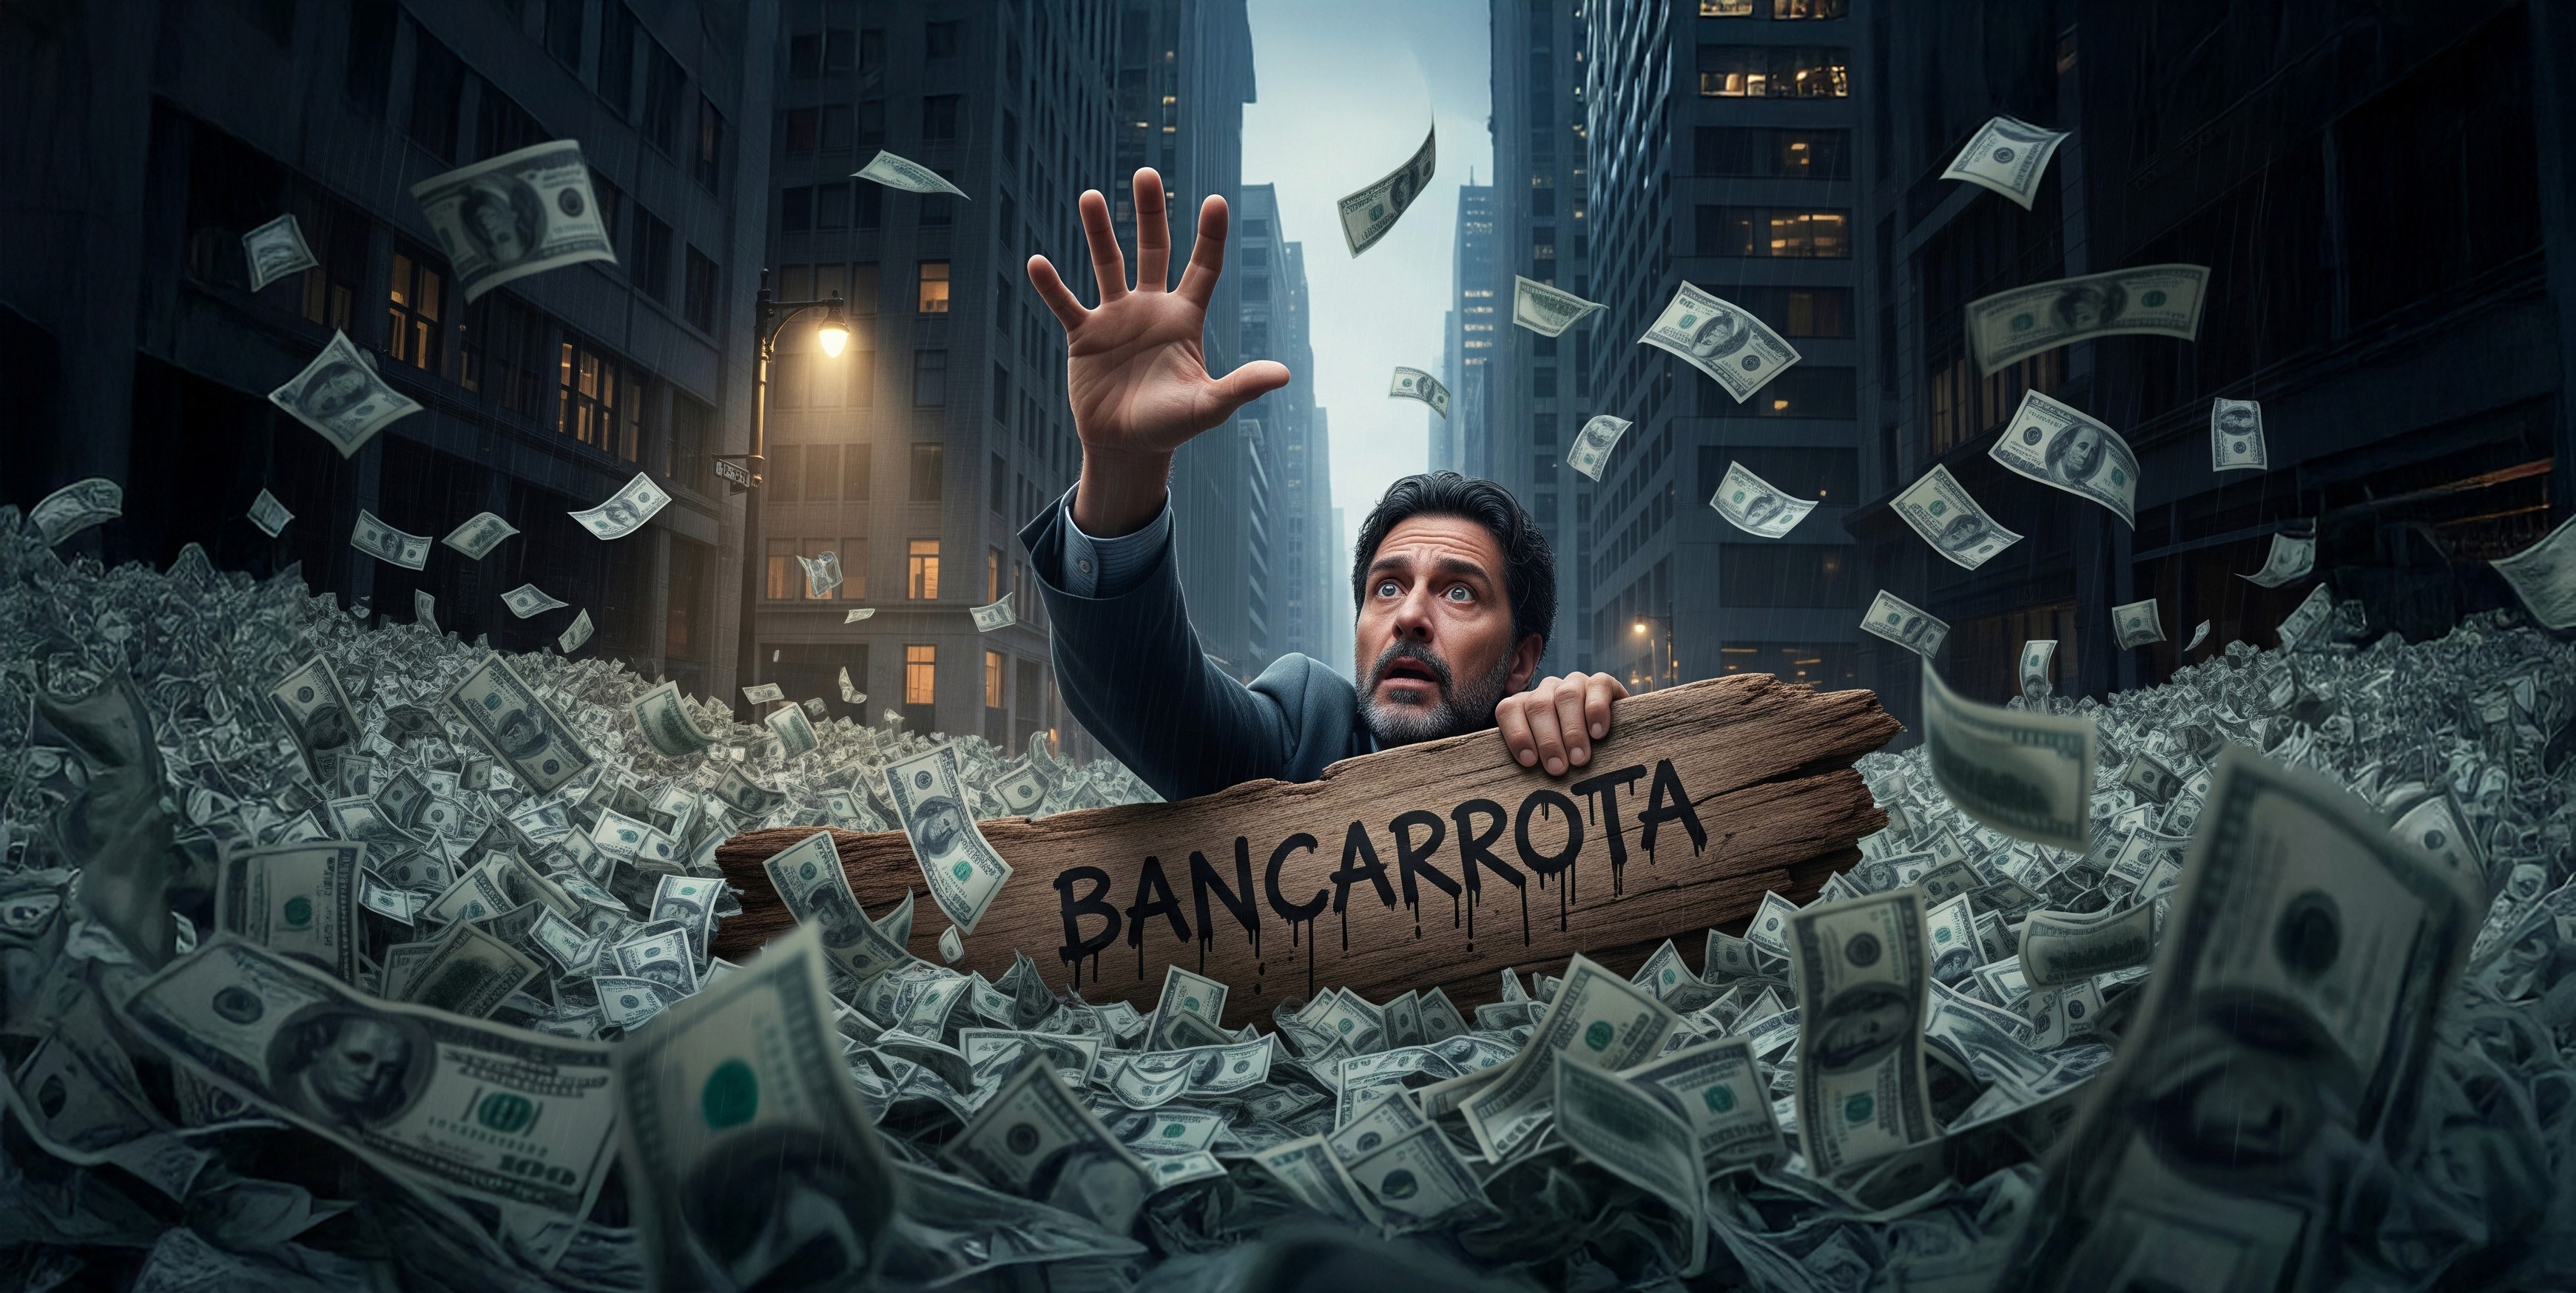
Bankruptcy is a legal tool designed to offer a "fresh start," so to speak, to those who cannot meet their financial obligations, while also protecting creditors by establishing an organized system to recover part of their money.
Bankruptcy is considered the measure of last resort for a debt problem that generally requires liquidating assets or signing a payment plan.
How does bankruptcy work?
When you file for bankruptcy, you are informing the court system that you cannot pay your debts. Being a legal process and not a program, it typically requires the debtor to file a petition with a bankruptcy court, and it is this court that oversees the process and decides how to handle your assets and financial obligations.
The court judge will be the one to decide whether part of the petitioner's assets should be liquidated or if the debt can be restructured to satisfy as much of the obligation as possible.
Although the duration of the process varies depending on the type of bankruptcy, you can expect between 3 and 6 months for Chapter 7, between 3 and 5 years for Chapter 13, and from several months to several years for Chapter 11. We will discuss these 3 types of bankruptcy in more detail below.
Automatic stay
Once the bankruptcy petition is filed, an automatic stay will go into effect, temporarily preventing creditors from taking collection actions against the debtor, including lawsuits, foreclosures, or wage garnishments.
341(a) Meeting
Following the automatic stay, a trustee will be assigned to oversee the case, and approximately one month after the bankruptcy filing, the 341 meeting, also known as the meeting of creditors, will take place, where the debtor must declare their assets, income, and debts.
The purpose of the 341 meeting is to examine the debtor's financial situation and confirm the facts declared by the debtor in the bankruptcy petition. The assigned trustee will determine if any of the assets should be sold in liquidation cases (Chapter 7) or if a payment plan is needed in reorganization cases (Chapter 13).
This meeting is also aimed at helping the debtor understand the bankruptcy procedure while allowing creditors and other interested parties to ask questions about their financial situation. It is mandatory for the debtor to attend the 341 meeting and answer questions under penalty of perjury; however, it is not mandatory for creditors to attend.
Discharge
At the end of the process, qualifying debts will be discharged, meaning the debtor will no longer be legally responsible for them as long as they comply with the terms of the bankruptcy.
The discharge is a permanent order and prohibits the debtor's creditors from taking any type of collection action on the discharged debts.
It is important to consider that a valid lien that has not been avoided in the bankruptcy process will survive after the discharge. In other words, a secured debt that has been deemed unenforceable in the bankruptcy petition will remain the debtor's responsibility. Therefore, a secured creditor may enforce the lien to recover the collateral.
Can you file on your own?
Yes, there is an option to file for bankruptcy without the help of an attorney. Representing yourself is called filing "pro se"; however, it is not recommended at all because bankruptcy law is complex, has long-term financial and legal repercussions, and a single mistake can significantly harm the case.
It is preferable to go through the process with the support of a specialized bankruptcy attorney who knows how to choose which type of bankruptcy to file and how to navigate the legal process, which, we repeat, has long-term repercussions.
If you want to get more information about filing for bankruptcy on your own, start on the official US courts website uscourts.gov.
How much does it affect your credit history?
Bankruptcy is a highly negative credit event, considered by many lenders to be the worst possible.
The more accounts included in the bankruptcy filing, the greater the impact on your score. A person with a perfect credit history would experience a drastic drop in their score; on the other hand, a person with a negative history and a low score would experience only a slight drop.
Over time, the impact of a bankruptcy on credit gradually decreases, especially if you start building credit responsibly. However, bankruptcy will continue to affect your credit as long as it remains part of your credit report.
How long does it stay on your credit?
The amount of time a bankruptcy remains on your credit history depends on the type of bankruptcy. Generally, bankruptcies that discharge debts remain on the credit report the longest.
For example, a Chapter 7 bankruptcy can remain on the credit report for up to 10 years from the filing date because the debts were discharged, while a Chapter 13 bankruptcy typically remains for 7 years because the debts were restructured and part of the debt ends up being paid.
Types of Bankruptcy
Being under the United States Bankruptcy Code, bankruptcy types are referred to as "chapters" to facilitate identification and reference to legal provisions.
Chapter 7
Among the main types of bankruptcy is Chapter 7, which is liquidation bankruptcy.
Here, non-essential assets such as luxury properties or similar goods are sold to pay creditors, although assets like stocks and bonds can also be utilized. However, essential assets like the primary home, furniture, and the primary vehicle are protected from being liquidated.
Unsecured debts, such as credit cards or medical bills, are typically discharged.
Chapter 11
Chapter 11, which is primarily used by businesses, allows debts to be reorganized without closing the business, providing the opportunity to create profitability plans, reduce costs, and find new ways to increase revenue.
Basically, the company continues its operations while working on a debt repayment plan under court supervision. This plan may involve downsizing, renegotiating contracts, or selling assets.
Although it is an opportunity to stay afloat, the company cannot expand its operations, take on new debt, or sell assets not specified in the reorganization plan without court approval.
Chapter 13
Chapter 13, which is reorganization bankruptcy, allows you to keep your assets (including non-essential ones) and instead reorganizes debts into a payment plan that can last between 3 and 5 years in order to satisfy part of the debt that creditors deem minimally sufficient and that is paid reasonably according to the debtor's income.
The last resort
Individuals with low incomes usually qualify for Chapter 7, individuals with high incomes for Chapter 13; and Chapter 11, although it can be filed by individuals, is more common among businesses with severe difficulties.
A bankruptcy is the last resort to a debt problem, remaining as a negative mark on your credit for between 7 and 10 years, and depending on the type, if you have assets, they may have to be liquidated to pay off part of those debts.
There are two alternatives that should be considered before filing for bankruptcy. Personally, we would consider the Debt Management program because it does not leave a negative mark on your credit and the negative impact is only short-term. You could also consider the Debt Settlement program, although it is not one we would choose ourselves because, like bankruptcy, it leaves a negative mark on your credit; however, it is an alternative if you do not want to go through the legal process of a bankruptcy.
More Posts