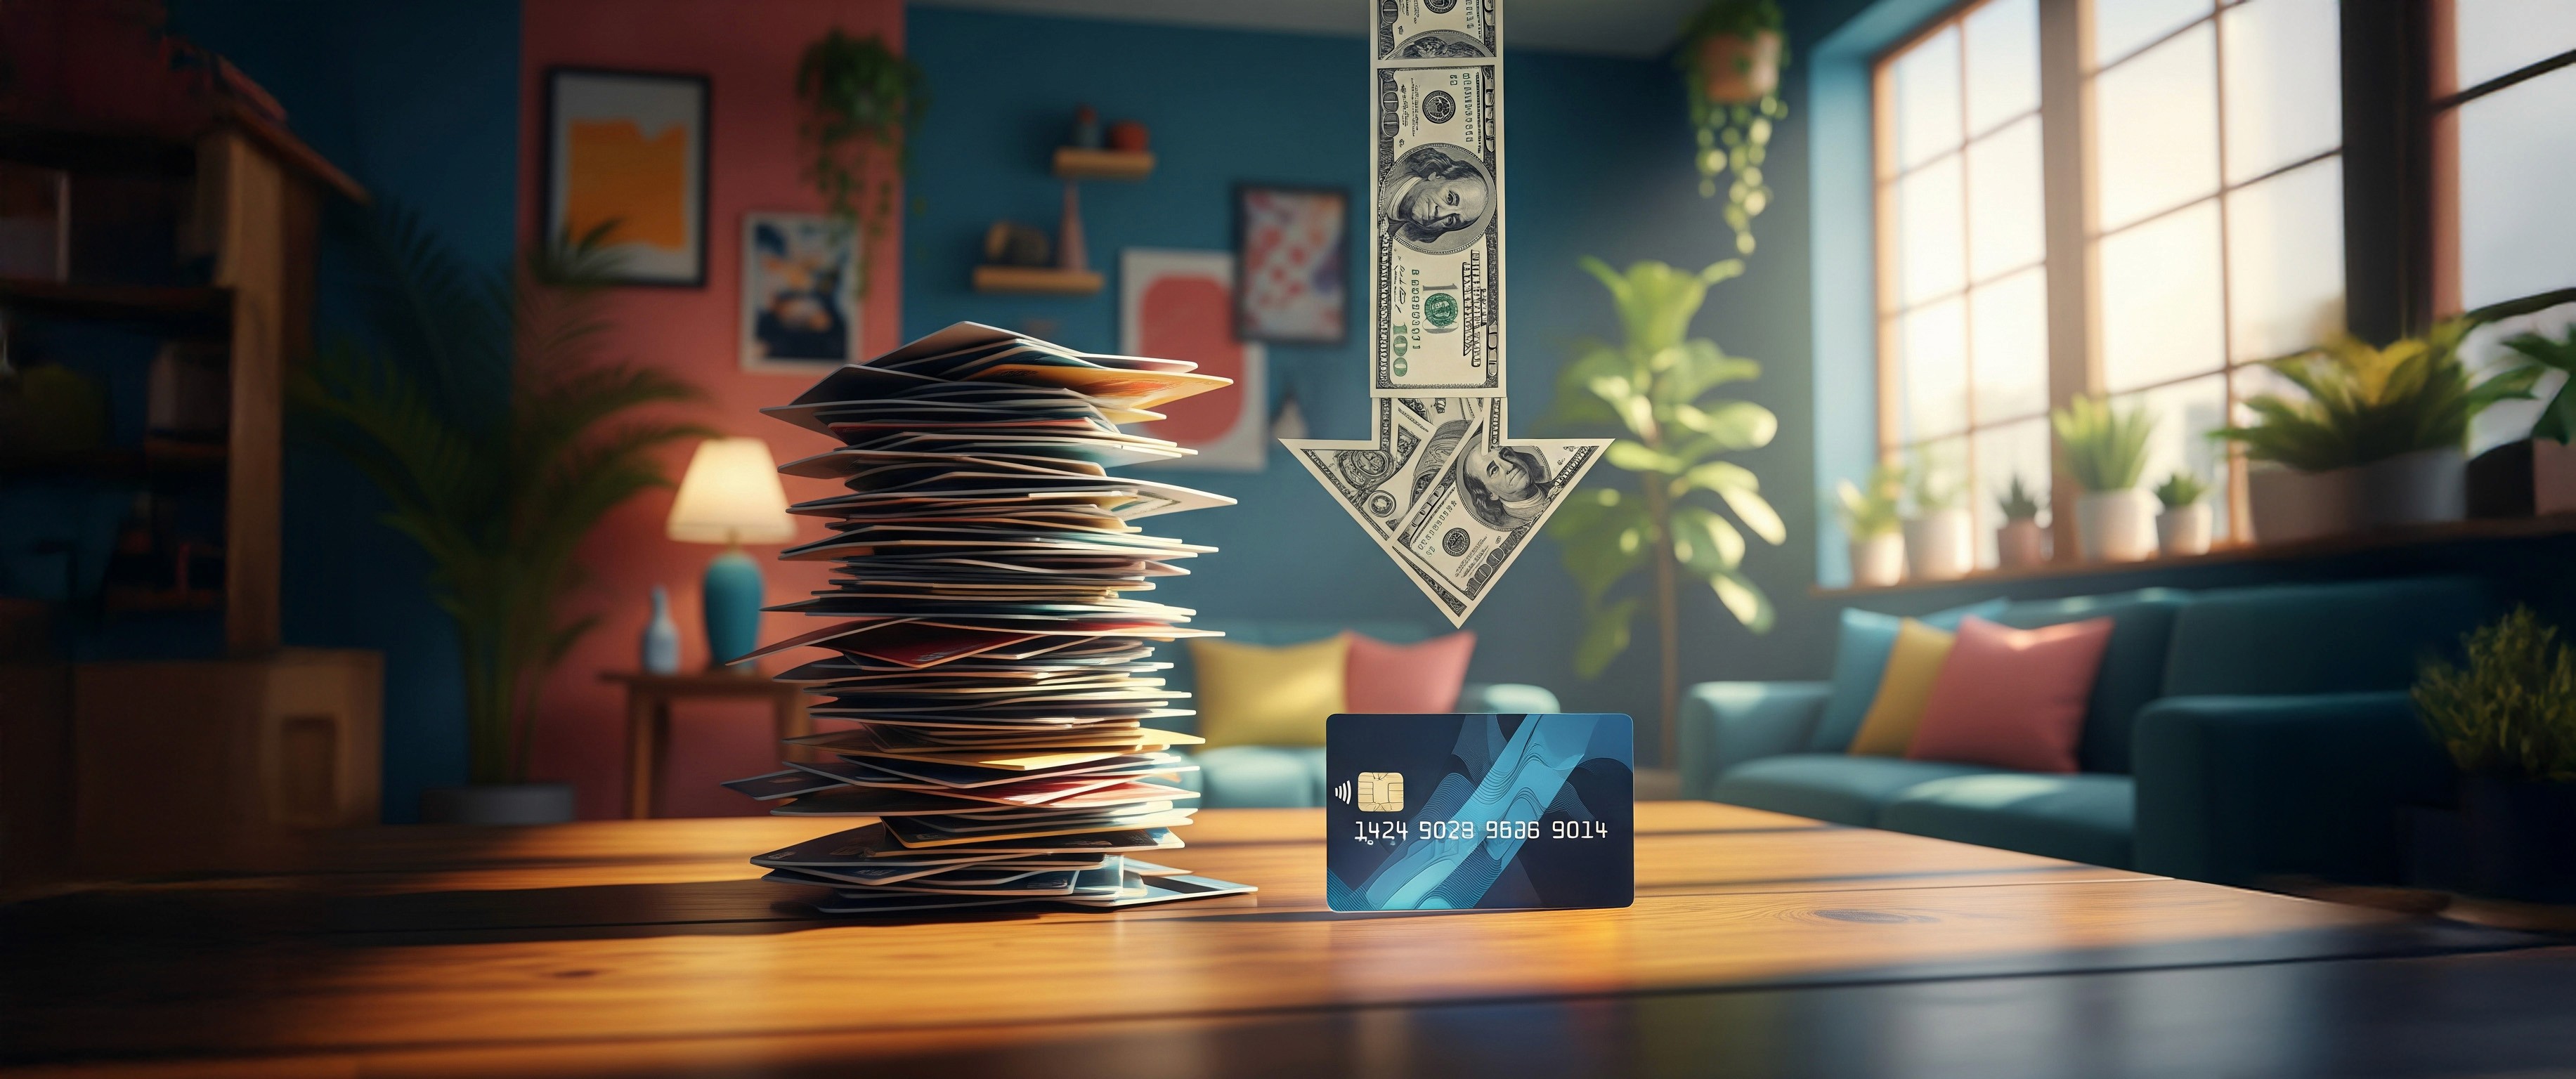
A balance transfer occurs when you move debt from one credit card to another. In simple terms, you are using a new card to pay off the balance you owe on another.
The main goal of a balance transfer is to reduce interest costs and make it easier to pay off debt. Many cards designed for this purpose offer an introductory 0% APR for a set period, typically 12, 15, 18 months, and in some cases even longer.
This can give you a window of time to directly tackle the principal of the debt without interest continuing to accumulate at the same rate.
But a balance transfer does not eliminate debt, nor is it a magic bullet. It simply moves the debt elsewhere and, when used correctly, can give you better terms to pay it off.
How Balance Transfers Work
Let's say you have $5,000 USD in debt on a credit card with an annual interest rate of 25% and you can pay $350 a month. It would take you 18 months to pay it off in full, and you would pay about $1,000 in interest during that time.
However, if you do a balance transfer to a card with 0% APR for 15 months, you will pay a fee of around 3% for transferring the debt, which would be $150 (this is added to your total debt), so now you would have a debt of $5,150 but at 0% APR for 18 months.
If you stick to the plan of paying $350 a month toward that debt and do not spend more on that card, you will pay it off in exactly 15 months and pay nothing in interest.
In total, you will have saved about $850, including the $150 fee.
The Risk with Balance Transfers
A person can become complacent with the 0% introductory APR, reduce the urgency to aggressively pay off the debt, and at the same time, continue using their cards, including this one. When the promotional period ends, some of the original balance still remains, and worse, new debt may have accumulated.
At that point, the initial plan to pay, for example, $350 a month may no longer be enough because the balance is no longer the same and interest begins to accumulate again.
One option could be to apply for another card and do a new balance transfer. However, this can easily become a cycle: moving debt from one card to another without actually reducing it.
In addition, each transfer usually includes a fee (typically 3% of the balance, but it can vary). In other words, even if you manage to avoid interest for a while, continuing to move debt comes with a cost.
That is why a balance transfer really works if: you stop accumulating new debt and you have a concrete plan to pay off the total balance before the 0% APR period ends.
When Should I Do a Balance Transfer?
There is no doubt that having a 0% APR can be a huge advantage, but this promotional period has an expiration date. The goal must be to reach that point with the balance completely paid off.
A balance transfer can be especially useful when an emergency forced us to use a credit card and we want to avoid paying high interest, but this must be accompanied by a clear payment plan.
For example, if you transfer a $5,000 balance and have 12 months at 0%, you would need to pay approximately $417 a month to eliminate the debt before the promotion ends.
We have used balance transfers in the past, and they can be an excellent tool to save on interest, as long as you have a strategy to pay off the debt before the introductory APR ends. Why do banks offer this?
Offering a 0% APR may seem unprofitable for the bank, but it is actually a strategy to attract new customers.
First, banks usually charge a transfer fee, averaging 3% of the total balance, so they generate revenue from the moment the transfer is made.
Furthermore, they know that not all customers will manage to pay off the full balance before the promotional period ends. When that happens, the remaining balance begins to generate interest at the card's regular APR, and that is where they begin to make more money.
There is also the possibility that the new customer will start using the card for other purchases, generating new balances and a more profitable long-term relationship.
In short, the bank gains a new customer, charges an initial fee, and has the potential to generate additional revenue in the future. That is why balance transfer offers can be attractive to both the consumer and the bank.
Do Balance Transfers Hurt Your Credit?
A balance transfer can temporarily affect your credit score because you are applying for a new card, as this typically involves a hard inquiry to your credit.
However, in the long run, it could also help improve your score if the new card increases your available credit and, therefore, reduces your credit utilization ratio.
Mind you: this benefit only remains if you do not run up balances on your other cards again. If you transfer the debt but then start using your previous cards again, your utilization could increase again and negatively affect your credit.
More Posts